$160,000 a Year After Tax in Washington
A single filer earning $160,000 in Washington takes home about $9,975 a month, or $119,698 a year, after federal income tax, FICA and state tax. Change the filing status, add a 401(k) or HSA, or name a city, and the figure below moves with you.
Adjust it to your situation
| Line item | Annual | Monthly |
|---|---|---|
| Gross pay | $160,000 | $13,333 |
| Pre-tax deductions (401k / HSA) | -$0 | -$0 |
| Federal income tax | -$27,134 | -$2,261 |
| Social Security | -$9,920 | -$827 |
| Medicare | -$2,320 | -$193 |
| Washington state income tax No state income tax | -$0 | -$0 |
| Local / state payroll tax | -$928 | -$77 |
| Take-home pay | $119,698 | $9,975 |
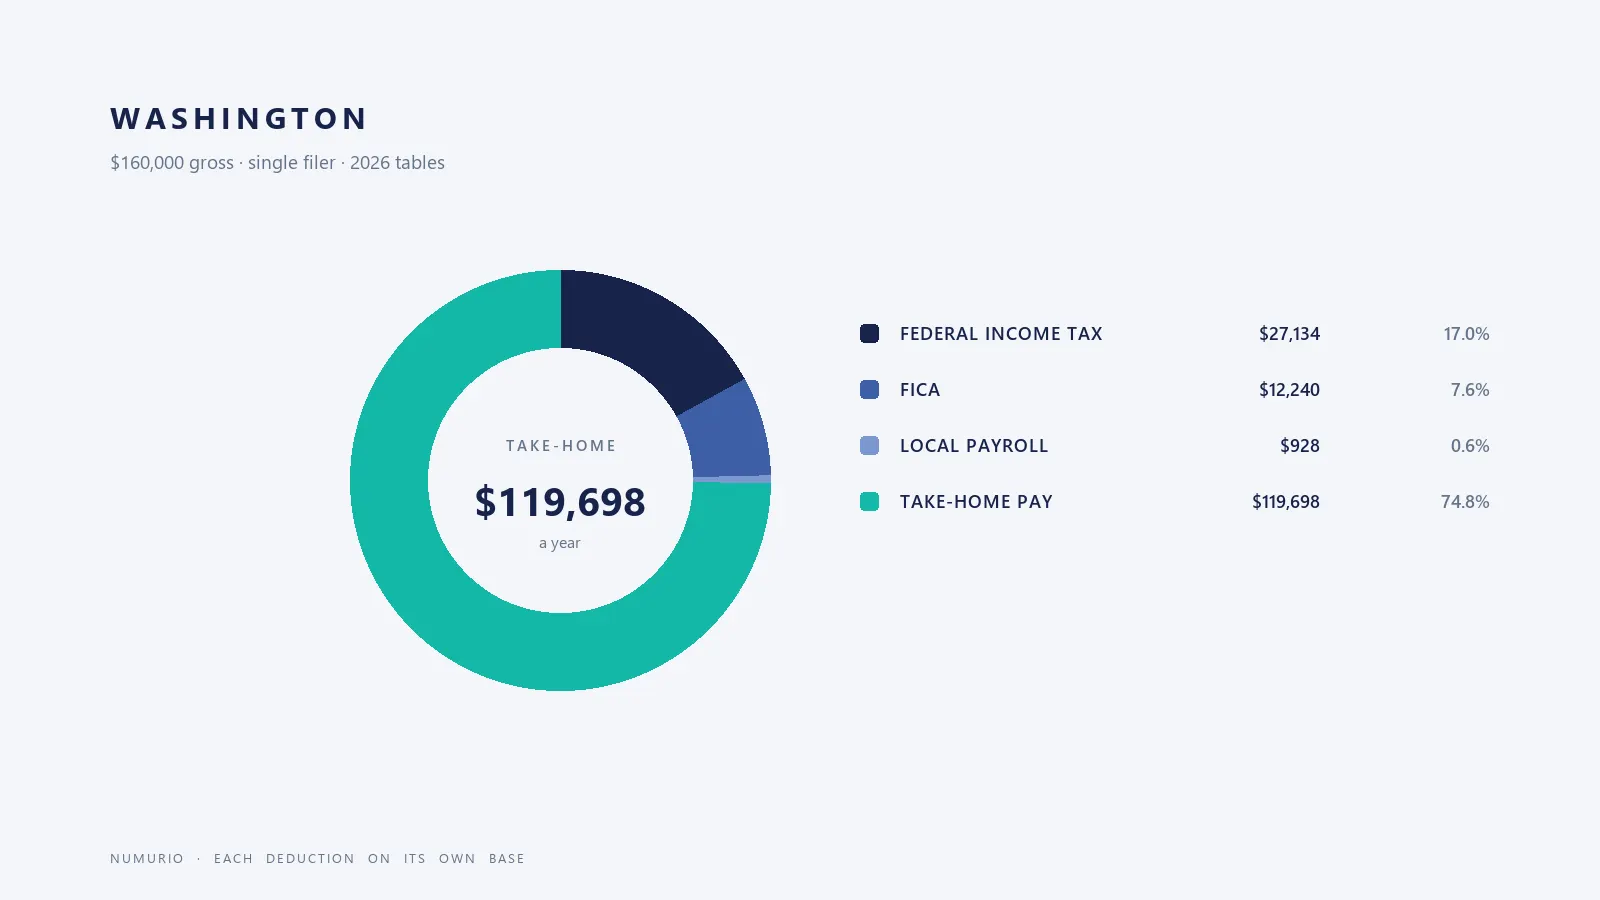
- Federal income tax$27,13417.0%
- FICA (Social Security + Medicare)$12,2407.6%
- Local / state payroll tax$9280.6%
- Take-home pay$119,69874.8%
Why $160,000 does not mean $160,000 in your account
The gap between gross and net is built from three separations, and they are not the same kind of calculation. The federal piece is banded: every band of taxable income carries its own rate, so no single percentage describes the whole salary. Social Security charges 6.2% until the wage base and stops; Medicare charges 1.45% on every dollar past it. The last separation belongs to Washington.
Washington has no state income tax, so that third layer is zero. The state funds itself through other taxes, which do not appear on a paycheck but do affect what you keep over a year.
These figures assume a single filer, the standard deduction and no pre-tax entries. The payroll levy at 0.6% is already in the figures above because it comes off every cheque in Washington. A city or county income tax is not in the dataset.
The arithmetic, line by line
Nothing is hidden in the arithmetic: this is the list the calculator returned, unchanged, at the defaults above. Every line is a base times a rate, and every rate is in the source list.
| Line | Annual | Monthly (12) | Semi-monthly (24) | Bi-weekly (26) | Weekly (52) |
|---|---|---|---|---|---|
| Gross pay | $160,000 | $13,333 | $6,667 | $6,154 | $3,077 |
| Pre-tax deductions (401k / HSA) | -$0 | -$0 | -$0 | -$0 | -$0 |
| Federal income tax | -$27,134 | -$2,261 | -$1,131 | -$1,044 | -$522 |
| Social Security | -$9,920 | -$827 | -$413 | -$382 | -$191 |
| Medicare | -$2,320 | -$193 | -$97 | -$89 | -$45 |
| Washington state income tax | -$0 | -$0 | -$0 | -$0 | -$0 |
| Local / state payroll tax | -$928 | -$77 | -$39 | -$36 | -$18 |
| Take-home pay | $119,698 | $9,975 | $4,987 | $4,604 | $2,302 |
Monthly, semi-monthly, bi-weekly and weekly columns are the annual amount divided by 12, 24, 26 and 52. Those are averages, not a payroll formula. A payroll system runs the IRS percentage method on every cheque, which is why a bonus month can withhold above this average and settle up at filing. Past the Social Security wage base the 6.2% stops, and the cheques after that point come out higher.
Married, filing jointly, on the same salary
The table above is one person's return throughout. If this $160,000 is the household's only income and the couple files jointly, the standard deduction doubles and each federal bracket covers twice the income before the next rate begins, so the same gross salary keeps $9,594 more a year. Most of the gap comes from the federal side; because Washington has no income tax, the state line contributes nothing either way.
| Pay period | Single filer | Married, filing jointly | Difference |
|---|---|---|---|
| Annual | $119,698 | $129,292 | $9,594 |
| Monthly (12) | $9,975 | $10,774 | $800 |
| Bi-weekly (26) | $4,604 | $4,973 | $369 |
The comparison holds for a single earner. Split the same money between two people and each employer withholds against its own employee, so the household can end up in a bracket neither payslip shows on its own. Put both incomes into the calculator first.
$160,000 against the federal table, FICA and the state schedule
After the $16,100 standard deduction, $143,900 of this salary is subject to federal income tax. The last dollar of it sits in the 24.0% bracket, which starts at $105,700. Another $57,875 of gross pay, $57,875 more of taxable income, would push this salary into the 32.0% bracket, and only the money above that line would be taxed at the higher rate.
FICA does not tier. Under $184,500 it is 6.2% for Social Security plus 1.45% for Medicare, 7.65% of every dollar. Gross pay here is $24,500 below the wage base; past that line the 6.2% part stops and Medicare keeps going on its own.
| Position | Value here | Where it comes from |
|---|---|---|
| Federal taxable income | $143,900 | Gross $160,000 minus the $16,100 standard deduction |
| Federal bracket at the last dollar | 24.0% from $105,700 | $57,875 more gross pay to reach 32.0% |
| FICA on the next dollar | 7.65% full rate | $24,500 below the $184,500 wage base |
| State tax in Washington | No wage tax | Funded by property, sales and excise taxes instead |
| Salary against the Washington median wage | 2.8× | Median wage $56,325 · median household $99,389 |
Washington levies no tax on wage income, so the third layer in the stack above is zero. The state still funds itself through property, sales and excise taxes, but none of those appear on a paycheck, so the take-home figure here is purely federal tax plus FICA. On a $160,000 salary that is the difference a state line makes: nothing.
The tax code is only half the context. Measured against the state instead: the median wage in Washington is $56,325, so $160,000 is 2.8× the typical wage there. Household income in Washington runs to $99,389 at the median, and that figure assumes every earner under the roof contributes. A single salary set against it is not a like-for-like test.
Washington takes nothing from this salary
None of the $40,302 withheld here goes to Washington. Federal income tax is $27,134 and FICA is $12,240, and those two lines are the whole bill.
The same $160,000 in California leaves $108,055, so Washington keeps $11,643 more a year at this salary, $970 a month. That gap is the state income tax line and nothing else.
Payroll deductions Washington takes outside income tax
- Statewide payroll at 0.6%: WA Cares long-term care premium, withheld from wages; unrelated to income tax.
These come off every cheque and sit outside the income tax line, so a state with a low income tax rate can still take a larger share of gross. The dataset carries the statewide version of each, with no city or county equivalent.
What makes Washington different from a generic calculator
Washington does not tax wage income. It taxes long-term capital gains above a threshold, which is why the state shows a rate but no wage tax. Every paycheck still carries a 0.58% WA Cares long-term care premium.
Questions this page answers
- How much is $160,000 a year after tax in Washington?
- A single filer with no pre-tax contributions takes home about $119,698 a year, or $9,975 a month, in Washington. Total withholding is $40,302, an effective rate of 25.2% on gross pay.
- What marginal rate applies at $160,000 in Washington?
- Washington has no state income tax, so the marginal rate at $160,000 is federal plus FICA only: 24.0% federal and 7.65% FICA, 31.6% in total. That is the rate on the next dollar earned, not the average rate on the whole salary.
- How much does a 401(k) contribution change take-home at $160,000?
- Deferring $24,500 cuts this year's withholding by $5,880 at this salary: federal and Washington income tax fall, while FICA does not, because 401(k) deferrals sit outside the Social Security and Medicare base. Take-home falls by $18,620, and the $24,500 lands in the plan instead.
- How much is $160,000 a year bi-weekly after tax in Washington?
- Across 26 pay periods a single filer takes home about $4,604 per bi-weekly cheque, or $2,302 if you are paid weekly. On a joint return with no other income, the same salary works out at about $4,973 per cheque. These are annual figures divided by the number of periods, not an employer's per-cheque formula.
- Which costs does the $160,000 figure not include?
- Itemising, credits past the standard deduction, a second job, and local taxes the selector does not cover. It further assumes twelve months at this rate with no bonus, no vesting and no unpaid leave; a real payslip at the same annual rate usually lands elsewhere.
Every assumption behind this figure, and the order the deductions are applied in, is on the methodology page.
Same salary, no state income tax
Run $160,000 through the same federal table in a state that does not tax wages and only one line changes, or disappears. Where the cards below match, the state takes nothing from the cheque; where they do not, a state-run payroll programme is the reason.
Washington already levies no state income tax, and the comparison states are in the same position, so the cards below land on identical federal and FICA arithmetic. What can still move them is a payroll levy outside income tax. Washington's paid-leave premium is why its figure is a little lower.
Every salary from $25,000 to $250,000 has a page of its own in Washington. The full list is on the Washington index.
Other salaries in Washington
The same money, asked a different way
Gross pay is the entry point here. Two neighbouring questions run the same arithmetic from the other end: what this amount nets as a 1099 contractor, where self-employment tax replaces the employee's half of FICA, and what gross clears a stated monthly net.
Where these federal figures come from
5 documents carry the federal side of this page. The brackets and the standard deduction come from the IRS annual inflation notice, the Social Security wage base from the SSA, and the 401(k) deferral limit from the IRS contribution-limit notice. Each link below is the document the dataset was read from for tax year 2026.
- IRS IR-2025-103 / Rev. Proc. 2025-32: 2026 federal brackets and standard deduction
- SSA: 2026 Social Security wage base of $184,500
- IRS: 2026 401(k) elective deferral limit of $24,500
- Tax Foundation: State Individual Income Tax Rates and Brackets, 2026
- Illinois Department of Revenue: IL-700-T 2026 withholding booklet (4.95%, $2,925 exemption)
Dataset status VERIFIED · reviewed 2026-11-07. The full cross-market list lives on the sources page; the computation chain is on the methodology page.