$105,000 a Year After Tax in Minnesota
A single filer earning $105,000 in Minnesota takes home about $6,423 a month, or $77,081 a year, after federal income tax, FICA and state tax. Filing status, pre-tax contributions and your city all move this number, and the calculator below takes all three.
Adjust it to your situation
| Line item | Annual | Monthly |
|---|---|---|
| Gross pay | $105,000 | $8,750 |
| Pre-tax deductions (401k / HSA) | -$0 | -$0 |
| Federal income tax | -$14,270 | -$1,189 |
| Social Security | -$6,510 | -$543 |
| Medicare | -$1,523 | -$127 |
| Minnesota state income tax | -$5,617 | -$468 |
| Take-home pay | $77,081 | $6,423 |
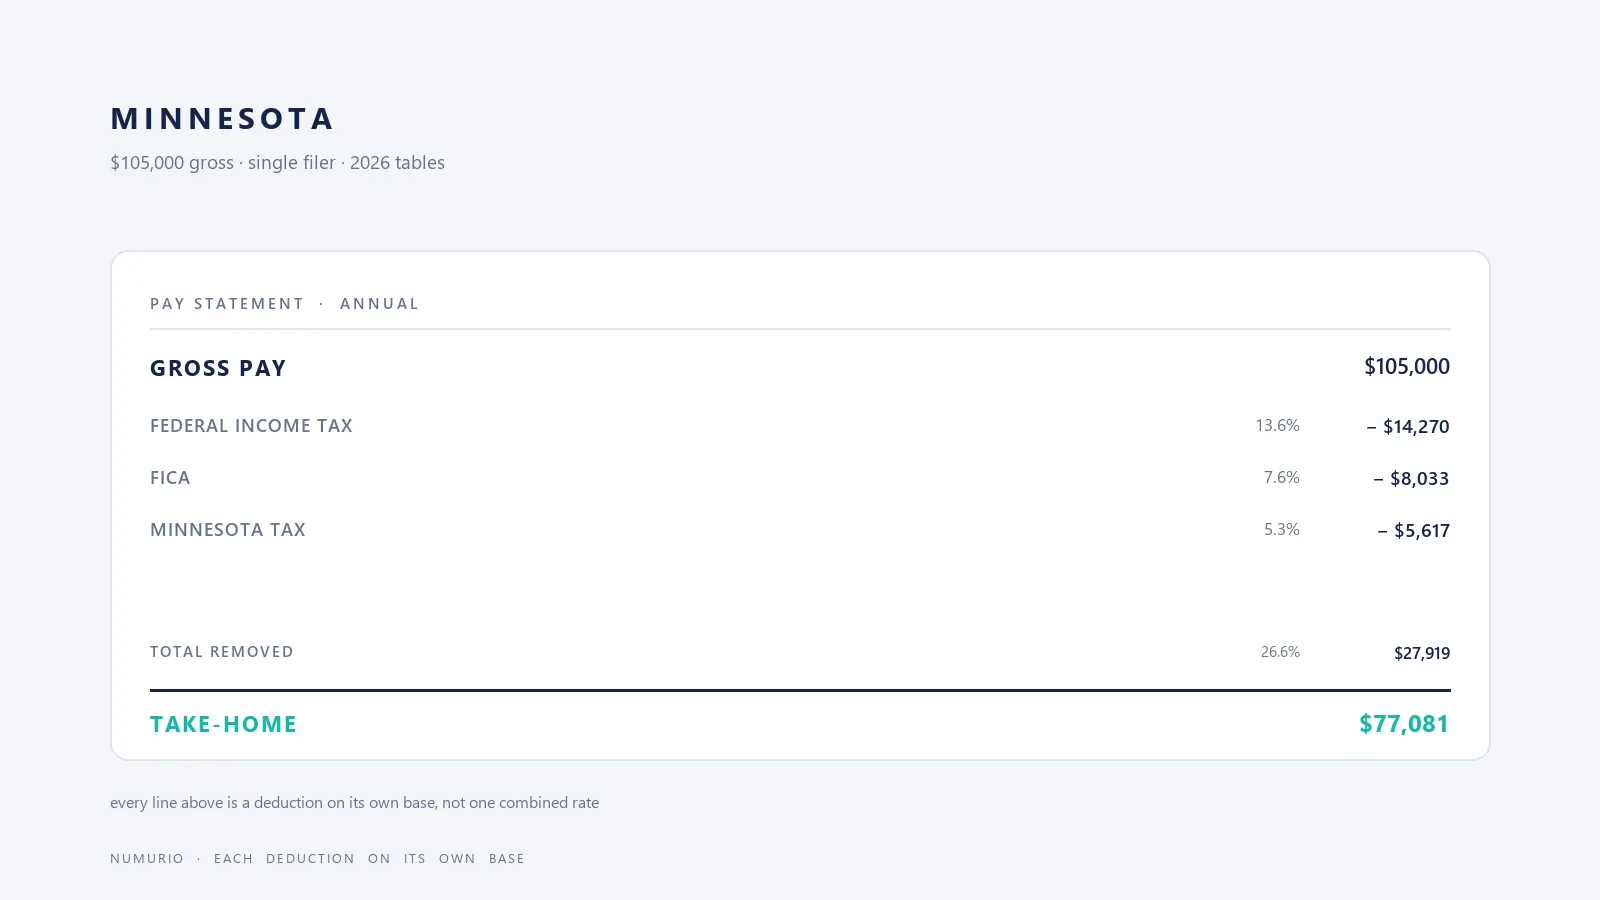
- Federal income tax$14,27013.6%
- FICA (Social Security + Medicare)$8,0337.6%
- Minnesota income tax$5,6175.3%
- Take-home pay$77,08173.4%
Where the $105,000 goes before it reaches your account
Two of the three deductions behave nothing alike. Federal income tax climbs band by band, so the rate on the last dollar sits well above the rate on the whole salary. FICA does not climb at all: 6.2% of each dollar up to the annual wage base, then 1.45% of each dollar with no ceiling. Minnesota adds the third line, and it applies its own schedule to income it defines itself.
Minnesota applies progressive brackets on top, so the same salary in a neighbouring state can land thousands of dollars apart over a year.
Nothing but the defaults: one filer, the standard deduction, both pre-tax fields blank. Minnesota's statewide schedule is modelled in full; the city and county add-ons that some localities levy are not in the dataset, so a resident of one of those places will see a lower figure on the cheque.
Every line of the calculation
No black box: this is the same list the calculator produced, at the defaults stated above. A base, a rate, and a source for the rate: all of it is in the source list.
| Line | Annual | Monthly (12) | Semi-monthly (24) | Bi-weekly (26) | Weekly (52) |
|---|---|---|---|---|---|
| Gross pay | $105,000 | $8,750 | $4,375 | $4,038 | $2,019 |
| Pre-tax deductions (401k / HSA) | -$0 | -$0 | -$0 | -$0 | -$0 |
| Federal income tax | -$14,270 | -$1,189 | -$595 | -$549 | -$274 |
| Social Security | -$6,510 | -$543 | -$271 | -$250 | -$125 |
| Medicare | -$1,523 | -$127 | -$63 | -$59 | -$29 |
| Minnesota state income tax | -$5,617 | -$468 | -$234 | -$216 | -$108 |
| Take-home pay | $77,081 | $6,423 | $3,212 | $2,965 | $1,482 |
Monthly, semi-monthly, bi-weekly and weekly columns are the annual amount divided by 12, 24, 26 and 52. Those are averages, not a payroll formula. Employers withholding per pay period use the IRS percentage method on each cheque, so a bonus month can withhold more than this average and refund it later; once the Social Security wage base is passed, later cheques in the year also come out higher because that 6.2% stops.
Married, filing jointly, on the same salary
Every figure above is a single filer. Filing jointly on the same $105,000, as the household's only income, widens the standard deduction and every federal band by the same factor, and $7,294 stays in the year instead of going to the IRS. Most of the gap comes from the federal side; some states widen their own brackets for joint filers too, which is why this is computed from the real Minnesota table rather than assumed.
| Pay period | Single filer | Married, filing jointly | Difference |
|---|---|---|---|
| Annual | $77,081 | $84,374 | $7,294 |
| Monthly (12) | $6,423 | $7,031 | $608 |
| Bi-weekly (26) | $2,965 | $3,245 | $281 |
This is one earner throughout. If two people each earn half of it, each employer withholds against a separate payslip, and the two incomes can add up into a higher bracket than either one implies. Enter both incomes in the calculator before relying on the joint column.
How $105,000 divides between the three tables
$88,900 of this salary clears the $16,100 standard deduction, and that is the federal base. The 22.0% band opens at $50,400, so the last dollar still lands inside it. The 24.0% band opens at $105,700 of taxable income, $16,800 away, or $16,800 in gross pay, and only income past that line would carry the higher rate.
FICA behaves the same at every salary below $184,500: 6.2% for Social Security plus 1.45% for Medicare, 7.65% in total, flat and with no brackets. This salary sits $79,500 below the Social Security wage base, so the full rate still applies to your next dollar, and only the portion above $184,500 would escape the 6.2% part.
| Position | Value here | Where it comes from |
|---|---|---|
| Federal taxable income | $88,900 | Gross $105,000 minus the $16,100 standard deduction |
| Federal bracket at the last dollar | 22.0% from $50,400 | $16,800 more gross pay to reach 24.0% |
| FICA on the next dollar | 7.65% full rate | $79,500 below the $184,500 wage base |
| State tax in Minnesota | $5,617 at 6.8% marginal | $89,700 of state taxable income |
| Salary against the Minnesota median wage | 2.0× | Median wage $51,228 · median household $87,117 |
Minnesota taxes wages with brackets, not a flat rate. At $89,700 of state taxable income the last dollar is taxed at 6.8%, and the state line totals $5,617 for the year. The next band at 7.8% begins at $109,430 of taxable income, $19,730 above where this salary lands, before any state deduction is added back.
Leave the tax tables for a moment and set the salary against the state itself: the median wage in Minnesota is $51,228, so $105,000 is 2.0× the typical wage there. The median household there brings in $87,117, and that is a household total. One salary against a two-income median understates where this payslip sits.
What $1,000 more would add at $105,000
$1,000 more gross at this level leaves $636 of it, 63.5% of the raise. The other $365 goes to $220 federal, $68 Minnesota, $77 FICA.
The average rate on the whole salary is 26.6%, so the raise is kept at a different share than the salary as a whole. The first dollars of the salary filled the bands below; the next thousand meets only the rates at the top.
Which Minnesota brackets $105,000 actually touches
Minnesota tax is charged on $89,700 of taxable income, which is gross pay minus the state standard deduction. The rate in the last row reaches only the dollars inside that band, not the salary as a whole.
| Band | Rate | Income in this band | Tax from this band |
|---|---|---|---|
| $0 – $33,310 | 5.3% | $33,310 | $1,782 |
| $33,310 – $109,430 | 6.8% | $56,390 | $3,835 |
| Total | 6.8% marginal | $89,700 | $5,617 |
The next 7.8% band starts at $109,430 of taxable income, which is about $124,730 of gross pay at this deduction level. Anything earned above that is taxed at 7.8% by Minnesota on top of federal and FICA.
What makes Minnesota different from a generic calculator
The Minnesota schedule has 4 tiers; only the slice above 203,150 dollars meets the 9.85% rate. By top rate, this state ranks 7th of the 42 taxing jurisdictions compared here.
Why $105,000 in Minneapolis nets $77,080.90
Minnesota runs one of the steepest state schedules in the Midwest, with four tiers rather than a single flat rate, and at $105,000 the state bill is $5,616.61 — more than three times what a flat-rate state would charge at the same salary. Federal tax is $14,270 and FICA is $8,032.50, leaving $77,080.90 a year, $6,423.41 a month.
The trade is deliberate: Minnesota funds a broader public sector, and the withholding line is where that shows up on a pay stub.
$105,000 in Minneapolis, Minnesota — single filer, no pre-tax contributions
| Line | Amount | Why it is that size |
|---|---|---|
| Gross salary | $105,000 | Full year at this rate |
| Federal income tax | $14,270 | After the $16,100 standard deduction |
| Social Security (6.2%) | $6,510 | Below the $184,500 wage base |
| Medicare (1.45%) | $1,522.50 | No additional 0.9% at this salary |
| Minnesota income tax | $5,616.61 | Four-tier progressive schedule |
| City income tax | $0 | Minneapolis does not levy a wage tax |
| Take-home, annual | $77,080.90 | 73.4% of gross |
| Take-home, monthly | $6,423.41 | Annual ÷ 12 |
| Take-home, bi-weekly | $2,964.65 | 26 pay periods |
Married filing jointly keeps $84,374.45, $7,293.55 more. Unlike a flat-rate state, part of that gain is state-level as well as federal, because Minnesota's brackets widen for joint filers. The practical consequence for a two-earner Minneapolis household is that married-filing-jointly is modelled as one combined income — which is not the same thing as two separate salaries, and the difference is usually a penalty when both earners are near the same level.
What this page does not model
No property tax, no sales tax, no 401(k) or HSA contributions, no itemised deductions, and no city wage tax. Minnesota also has its own treatment of certain income types outside wages, which this page does not touch.
- Why is Minnesota's state bill so much larger than a flat-rate state's?
- $5,616.61 at $105,000, against roughly $1,700-2,500 in a low flat-rate state at the same salary. The difference is the progressive schedule: most of this income sits above the lowest tiers rather than at one rate for the whole base.
- Does Minneapolis add a city income tax?
- No. The city does not levy a wage tax, so the state schedule is the entire local picture on this page.
Questions this page answers
- How much is $105,000 a year after tax in Minnesota?
- A single filer with no pre-tax contributions takes home about $77,081 a year, or $6,423 a month, in Minnesota. Total withholding is $27,919, an effective rate of 26.6% on gross pay.
- What marginal rate applies at $105,000 in Minnesota?
- At $105,000 the last dollar is taxed at 22.0% federally and 6.8% by Minnesota, plus 7.65% FICA, or 36.5% combined. {effectiveRateNote(seed, formatPct(single.effectiveRate))}
- How much does a 401(k) contribution change take-home at $105,000?
- Deferring $24,500 cuts this year's withholding by $7,056 at this salary: federal and Minnesota income tax fall, while FICA does not, because 401(k) deferrals sit outside the Social Security and Medicare base. Take-home falls by $17,444, and the $24,500 lands in the plan instead.
- How much is $105,000 a year bi-weekly after tax in Minnesota?
- Across 26 pay periods a single filer takes home about $2,965 per bi-weekly cheque, or $1,482 if you are paid weekly. Filing jointly on the same salary as the household's only income comes to about $3,245 per cheque. Read the columns as the annual figure cut into equal slices. Employers withhold against those tables rather than against this average, which is why a single stub can differ.
- What is left out of the $105,000 figure on this page?
- Anything the form above does not ask for: itemised deductions, extra credits, a second job, a local tax. The salary is also treated as a full year of work, without a bonus, equity or unpaid leave, and a real payslip at that annual rate rarely matches month to month.
Every assumption behind this figure, and the order the deductions are applied in, is on the methodology page.
Same salary, no state income tax
The same $105,000 in the jurisdictions that levy no state income tax. Federal income tax and FICA are identical in all of them, so any gap in the cards below comes from a payroll levy rather than from an income tax.
At this salary Minnesota leaves $77,081 a year, while Texas, which has no state income tax at all, leaves $82,698, a difference of $5,617 created by the state income tax line and nothing else.
Every salary from $25,000 to $250,000 has a page of its own in Minnesota. The full list is on the Minnesota index.
Other salaries in Minnesota
The same figure, three other entry points
Here the gross figure is given and the net is the answer. Two other entry points reverse that: the same amount as a 1099 contractor, where self-employment tax takes the place of the employee's half of FICA, and a monthly net target, worked back into the gross that produces it.
Where these federal figures come from
5 documents carry the federal side of this page. The brackets and the standard deduction come from the IRS annual inflation notice, the Social Security wage base from the SSA, and the 401(k) deferral limit from the IRS contribution-limit notice. Each link below is the document the dataset was read from for tax year 2026.
- IRS IR-2025-103 / Rev. Proc. 2025-32: 2026 federal brackets and standard deduction
- SSA: 2026 Social Security wage base of $184,500
- IRS: 2026 401(k) elective deferral limit of $24,500
- Tax Foundation: State Individual Income Tax Rates and Brackets, 2026
- Illinois Department of Revenue: IL-700-T 2026 withholding booklet (4.95%, $2,925 exemption)
Dataset status VERIFIED · reviewed 2026-11-07. The full cross-market list lives on the sources page; the computation chain is on the methodology page.