£75,000 after tax in Scotland, 2026/27
£75,000 a year comes out at £52,007 after income tax and National Insurance — £4,334 a month, or £1,000 a week. Add the statutory 5% workplace pension and it becomes £50,730 a year, because the pension is taken before income tax.
Change the number
Before tax and pension. Use the yearly figure, not monthly.
The legal minimum is 5%. Your employer adds at least 3% on top.
Repayments come out of pay through PAYE, before you see the money.
| Line | Per year | Per month |
|---|---|---|
| Gross salary | £75,000 | £6,250 |
| Workplace pension (employee) | −£2,202 | −£183 |
| Income Tax (PAYE) | −£18,557 | −£1,546 |
| National Insurance | −£3,511 | −£293 |
| Take-home pay | £50,730 | £4,228 |
Your employer also pays £1,321 a year into your pension on top of this — that money is not part of your take-home pay.
Where the £75,000 goes
| Line | No pension | 5% pension | Monthly, 5% pension |
|---|---|---|---|
| Gross salary | £75,000 | £75,000 | £6,250 |
| Workplace pension | — | −£2,202 | −£183 |
| Income tax | −£19,482 | −£18,557 | −£1,546 |
| National Insurance | −£3,511 | −£3,511 | −£293 |
| Take-home | £52,007 | £50,730 | £4,228 |
Salary sacrifice, and why the National Insurance line moves
The 5% pension figures above assume the money is deducted from pay — the net pay or relief at source arrangement. Income tax falls, but National Insurance is still charged on the full £75,000. A salary sacrifice works differently: what you give up is pay itself, so both bases fall. Same 5%, two different answers:
| Arrangement | Pension | Income tax | National Insurance | Take-home |
|---|---|---|---|---|
| Deducted from pay (net pay / relief at source) | −£2,202 | −£18,557 | −£3,511 | £50,730 |
| Salary sacrifice | −£2,202 | −£18,557 | −£3,467 | £50,775 |
The gap is £44 a year at this salary — the employee National Insurance that is no longer charged on the sacrificed amount, plus the small effect on the personal allowance where it tapers. Two limits are not modelled here: sacrifice cannot take pay below the National Minimum Wage, and some schemes calculate pensionable pay on the post-sacrifice figure, which changes what the employer contributes. Ask payroll which arrangement you are actually on before using either column.
Which thresholds £75,000 sits between
UK deductions are not one smooth percentage — they switch at fixed points. This is where £75,000 falls, which explains the marginal rates you will see on a payslip at this level.
| Threshold | Level | Status at £75,000 | What it means here |
|---|---|---|---|
| Personal allowance and NI start | £12,570 | Above | Below this, no income tax and no NI |
| NI drops to 2% | £50,270 | Above | Also the top of the 20% band outside Scotland |
| Personal allowance starts shrinking | £100,000 | Below | Not reached |
| Personal allowance gone | £125,140 | Below | Not reached |
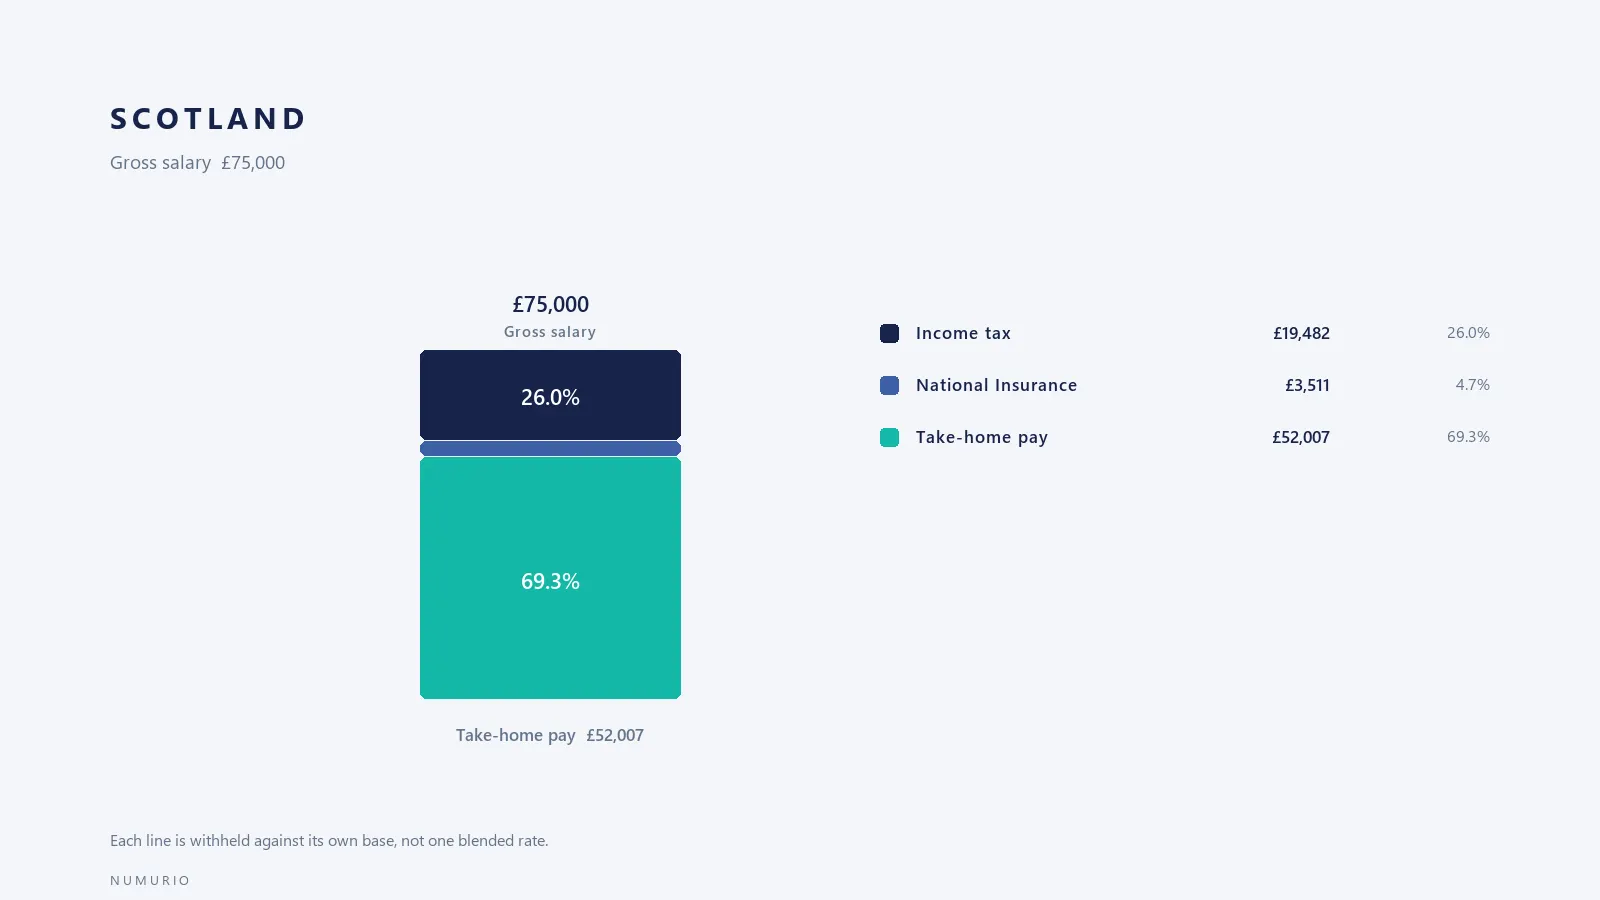
- Income tax£19,48226.0%
- National Insurance£3,5114.7%
- Take-home pay£52,00769.3%
Scotland against England, Wales & NI at £75,000
Identical salary, both tax systems, no pension: Scotland leaves £52,007 and England, Wales & NI leaves £54,057. The difference of £2,050 comes entirely from income tax bands — National Insurance is the same in both.
Student loan at this salary
£75,000 is above the repayment threshold for 5 plans, so a graduate on any of them would see a deduction: Plan 1 at £4,329 a year (9% above £26,900); Plan 2 at £4,105 a year (9% above £29,385); Plan 4 at £3,708 a year (9% above £33,795); Plan 5 at £4,500 a year (9% above £25,000); postgraduate loan at £3,240 a year (6% above £21,000).
Nearby salaries in Scotland
Is £75,000 a good salary in Scotland?
That depends on household size, housing costs and pension, which this page cannot know. What it can say: at £75,000 you keep £4,334 a month before pension, and 30.7% of gross goes to income tax and National Insurance.
How much is that per week?
£1,000 a week after tax and NI, or £976 with the 5% pension included. UK payroll usually quotes monthly or weekly, never annual, so this is the figure to compare with rent.
What if I pay more into my pension?
Each extra 1% under a net pay arrangement cuts income tax at your marginal rate but leaves National Insurance untouched. At £75,000 your marginal income tax rate is 2471%, so an extra £1,000 into the pension saves roughly £24,710 in tax and costs -£23,710 in take-home. Under salary sacrifice the National Insurance line falls as well — see the two-arrangement table below.
Does salary sacrifice save more than a normal pension deduction at £75,000?
Yes — by about £44 a year at this salary, all of it National Insurance. A pension deducted from pay reduces income tax only, because NI is still charged on the full gross; a salary sacrifice gives up pay itself, so the NI base falls too. Both arrangements are priced at the same 5% in the table further down this page.